Section 179 · 2026
Section 179 in 2026: Deduct the Full Cost of Qualifying Medical Equipment This Year
For tax years beginning in 2026, Section 179 lets a qualifying practice deduct up to $2,560,000 of equipment placed in service by December 31. Plan purchases of patient monitors, anesthesia machines, and surgical tables and lights with that deadline in mind. Not tax advice. Consult your tax advisor about your situation.
- $2,560,000
- Most you can deduct under Section 179
- $4,090,000
- Purchases before the maximum shrinks
- $6,650,000
- Section 179 reaches $0 at
- Dec 31, 2026
- Placed in service by
Every dollar of 2026 purchases above $4,090,000 reduces the $2,560,000 maximum by one dollar. Example: $4,400,000 in purchases is $310,000 over, so the maximum becomes $2,250,000. Buying more doesn't shrink your total write-off, though: equipment that Section 179 can't cover can usually still be deducted in year one through 100% bonus depreciation, which has no dollar cap or phase-out.
What Section 179 Is
Section 179 of the Internal Revenue Code lets a business deduct the cost of qualifying equipment in the year it goes into service, rather than depreciating it over several years. It is a deduction, not a tax credit: it lowers taxable income, and the savings depend on your tax rate.
Section 179 is an election, not automatic. You (or your tax preparer) choose it on IRS Form 4562, Part I, for the equipment you want to expense.
The One Big Beautiful Bill Act (Public Law 119-21, July 2025) set the base limits at $2.5 million and $4 million, indexed for inflation. For tax years beginning in 2026, IRS Rev. Proc. 2025-32 sets them at:
2026 IRS limits
- Maximum deduction: $2,560,000
- Phase-out threshold: $4,090,000 of qualifying equipment placed in service in the year (the limit drops dollar for dollar above this amount)
- Full phase-out: the limit reaches $0 at $6,650,000
The same law made 100% bonus depreciation permanent for qualified property acquired after January 19, 2025. Your tax advisor can tell you which approach, or combination, fits your return.
Who Qualifies
Section 179 is available to taxable businesses, including:
Available to
- Private medical and dental practices (sole proprietors, partnerships, S corporations, LLCs, C corporations)
- Ambulatory surgery centers (ASCs)
- Outpatient clinics and urgent care centers
- Physician-owned surgery centers and specialty practices
Requirements:
- The equipment is used more than 50% for business.
- The deduction cannot exceed taxable business income for the year (unused amounts carry forward).
- The equipment is purchased or financed, including a $1 buyout lease. A true operating lease does not qualify.
- The equipment is acquired by purchase from an unrelated seller. Property bought from a related person (such as a spouse, parent, or child, or a business you own more than 50% of) or from another member of the same controlled group of corporations generally does not qualify (IRS Publication 946).
Tax-exempt hospitals and nonprofit clinics generally cannot benefit, because they do not owe income tax on their exempt activities.
Example of Equipment That Qualifies
Most tangible medical equipment used in your practice can qualify, new or refurbished (refurbished equipment must be new to your practice and bought from an unrelated seller). Examples Infinium Medical sells:

Refurbished GE Avance S5
View Product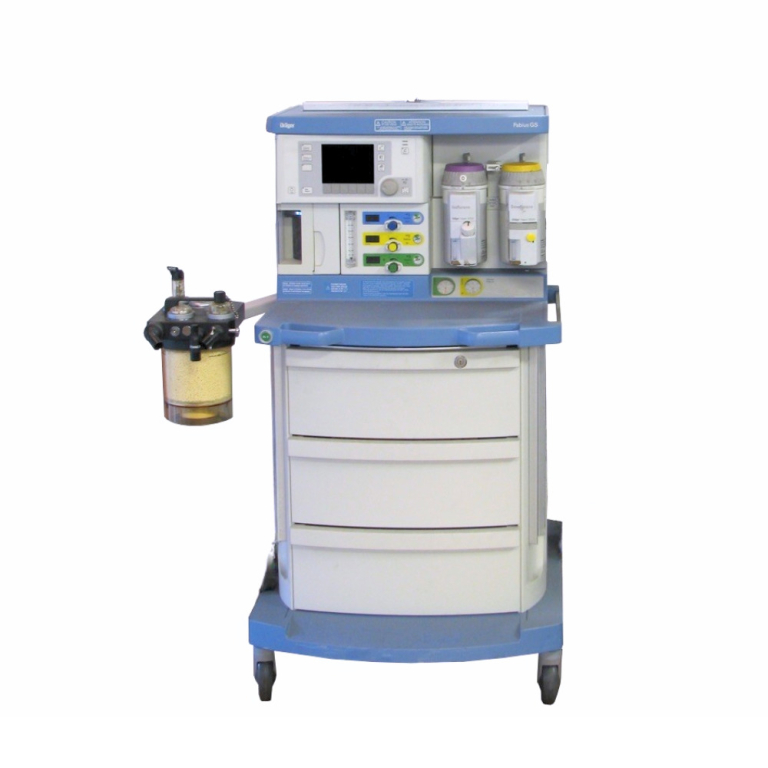
Refurbished Dräger Fabius GS
View Product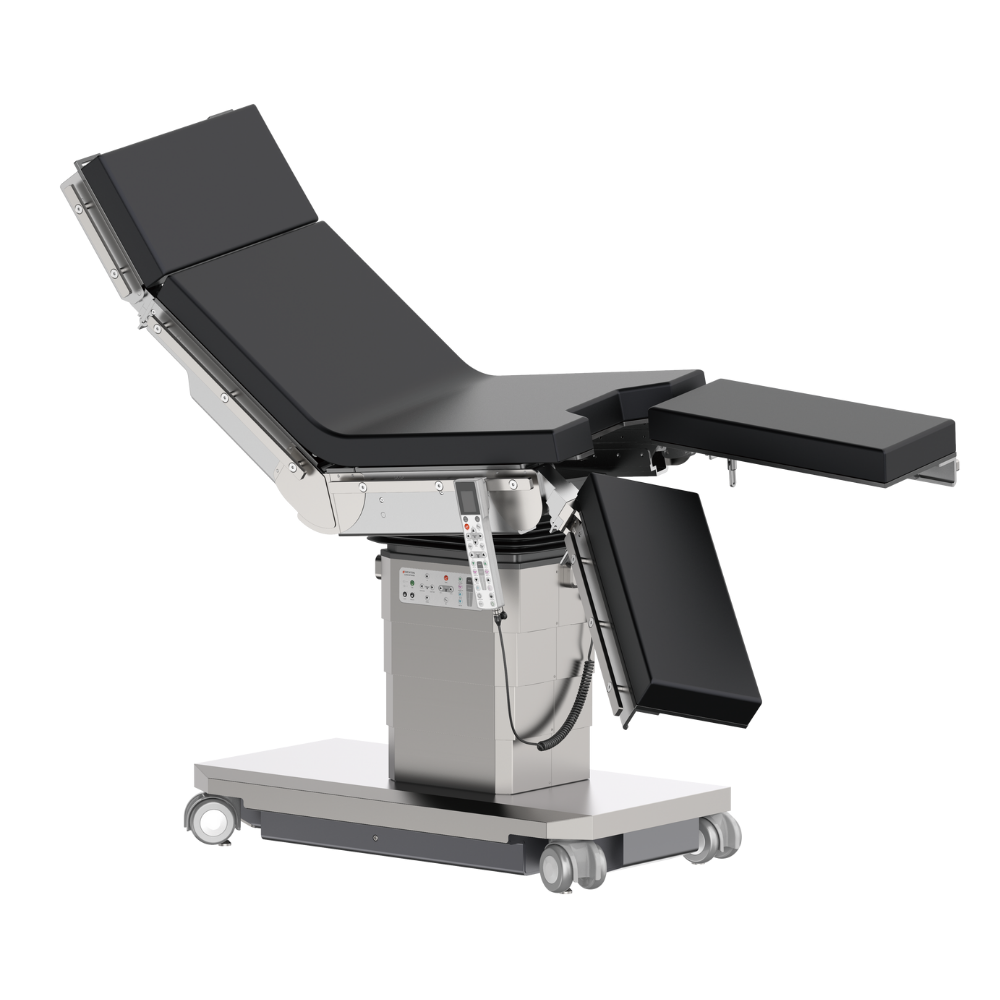
ST500 split-leg surgical table (1,000 lb)
View Product
S400 series operating room lights
View Product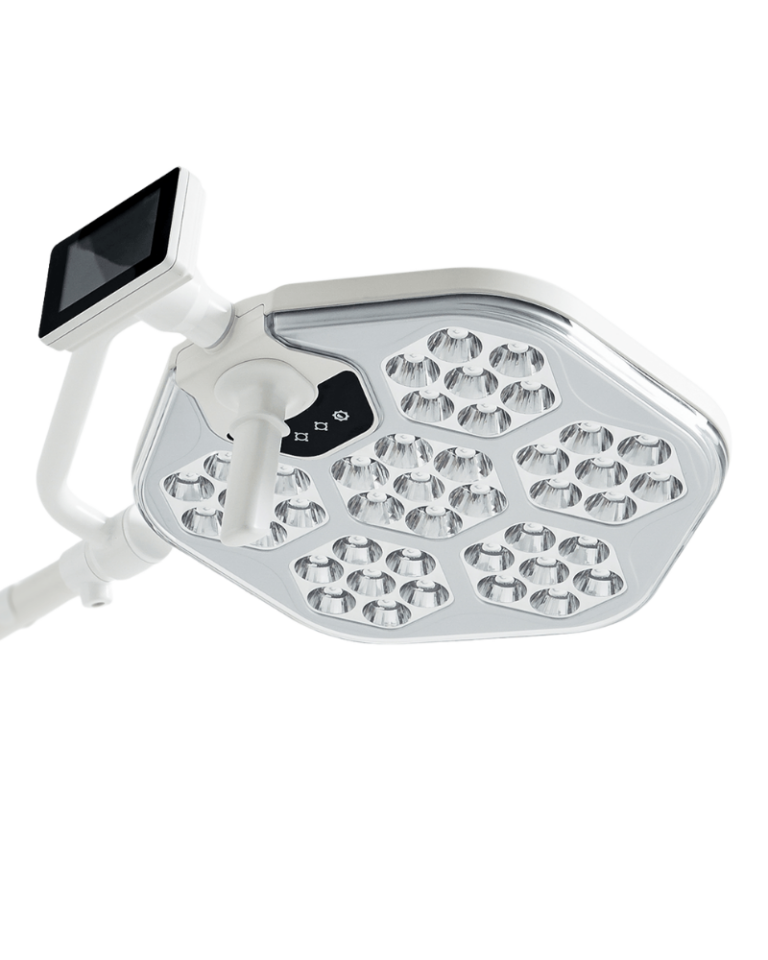
S300 surgical lights
View Product
Omni III high-acuity patient monitor
View Product
CLEO II vital signs monitor
View ProductTiming: In Service by December 31, 2026
The deduction applies to the year equipment is placed in service, meaning installed and ready for use. Ordering or paying in December is not enough. Allow time for shipping, delivery, installation, and staff in-service before year end. Contact us early in the fourth quarter to confirm lead times.
Placed in service by
Dec 31, 2026
Example
Worked Example
A surgery center outfits one operating room with new equipment: an ST500 surgical table, S400 surgical lights, an anesthesia machine, and an Omni III patient monitor, for an example total of $65,000 (example figure, not an Infinium price). It places the equipment in service in November 2026. Business use is 100%, total 2026 equipment purchases are under $4,090,000, and the center has more than $65,000 of taxable business income.
- Section 179 deduction: $65,000
- Estimated tax savings at a 35% combined rate: $22,750
- Effective net cost after the tax savings: $42,250
All dollar amounts are example figures, not Infinium prices. Your result depends on your entity type, income, state tax, and other deductions.

Checklist
Planning to Use Section 179?
-
Confirm your entity type and taxable income.
Section 179 helps taxable practices (sole proprietors, partnerships, S corporations, LLCs, C corporations). Ask your CPA to project 2026 taxable business income, since the deduction cannot exceed it.
-
Choose to buy or finance.
A cash purchase, an equipment loan, or a $1 buyout lease through DoctorsLoans can all qualify. A true operating lease (fair market value return) does not.
-
Order early enough to be in clinical use by December 31, 2026.
Build in time for shipping, delivery, installation, biomedical checkout, and staff in-service.
-
Keep your records.
Save the invoice, financing or lease agreement, delivery receipt, installation or in-service sign-off, and asset tag or serial numbers. The in-service date supports the tax year you claim.
-
Elect the deduction on IRS Form 4562
Part I, with your 2026 return.
-
Coordinate with your CPA
on how much to expense under Section 179 versus bonus depreciation, and on state treatment.
Financing still allows a full deduction
The deduction is based on the cost of the equipment, not the amount paid in cash during the year. A practice that finances a $65,000 OR package (example figure, not an Infinium price) with a small down payment can generally deduct the full $65,000 in 2026, as long as the equipment is in service by year end. A $1 buyout lease is treated like a purchase for this purpose. Infinium customers can apply for financing or a $1 buyout lease through DoctorsLoans. Loan interest is a separate expense, not part of the Section 179 amount.
Combining Section 179 with bonus depreciation
- Section 179 is elected item by item, up to $2,560,000 for 2026, and cannot create a business loss (excess carries forward).
- 100% bonus depreciation, made permanent for qualified property acquired after January 19, 2025, has no dollar cap and no business-income limit.
- A common approach: expense part of the cost under Section 179, then apply bonus depreciation to the rest. Your CPA chooses the mix based on income, losses, and state rules.
- Typical order: the Section 179 election comes first, bonus depreciation then applies to the remaining basis, and regular MACRS depreciation applies to anything left.
Compare
Section 179 vs. 100% Bonus Depreciation
| Feature | Section 179 | 100% bonus depreciation |
|---|---|---|
| 2026 dollar cap | $2,560,000 | No cap |
| Phase-out | Begins above $4,090,000; $0 at $6,650,000 | None |
| Business-income limit | Yes; excess carries forward | No; can create a loss |
| Election | Must elect on Form 4562 | Applies automatically unless you elect out |
| New and used | Both, if new to you and not from a related party | Both, if not previously used by you and not from a related party |
| Partial amount | Yes; choose the amount per item | No; applies to the whole class of property unless you elect out |
Sources: IRS Rev. Proc. 2025-32; IRS Publication 946.
State conformity caveats
States set their own rules. Some follow the federal Section 179 limits, some use lower limits, and some do not allow bonus depreciation, so the state deduction can be smaller than the federal one. Many states set their own, often lower, Section 179 limits or do not fully conform to federal bonus depreciation, so your federal and state results can differ. Ask your tax advisor how your state treats 2026 equipment purchases.
Common mistakes
- Ordering in December but not installing until January. The deduction follows the in-service date, so the deduction moves to 2027.
- Using an operating lease. Fair market value or rental agreements do not qualify for the lessee.
- Expecting a benefit at a tax-exempt hospital or nonprofit clinic. Without taxable income from the activity, the deduction provides no benefit.
- Claiming more than business income. The excess carries forward instead of reducing this year's tax.
- Mixed personal use at 50% or less. Equipment must be used more than 50% for business.
Real World Medical Scenarios
All dollar amounts below are EXAMPLE figures for new equipment at typical value-tier market levels. They are not Infinium prices. Request a Package Quote for actual pricing. Each example assumes the equipment is in service in 2026, total 2026 qualifying purchases (all business property) are under $4,090,000, 100% business use, and taxable business income covers the deduction. Tax rates are illustrative combined federal and state rates. Not tax advice.
Example
1. ASC operating room outfit (physician-owned LLC)
One OR: ST500 surgical table ($20,000 example), S400 dual-head surgical lights ($14,000 example), anesthesia machine ($25,000 example), Omni III patient monitor ($6,000 example). Example total: $65,000, financed with a $1 buyout lease through DoctorsLoans.
See the worked example and OR package graphic above.
- Deduction: $65,000
- Tax savings at 37%: $24,050
- Effective net cost: $40,950
Example
2. Two-room ASC expansion (S corporation)
Two OR outfits as above ($130,000 example) plus four CLEO II vital signs monitors for recovery ($12,000 example). Example total: $142,000.
- Deduction: $142,000
- Tax savings at 35%: $49,700
- Effective net cost: $92,300
Example
3. Physician practice adding in-office procedures (plastic surgery or podiatry, S corporation)
ST500 table ($20,000 example), S300 surgical light ($6,000 example), CLEO II vital signs monitor ($3,000 example). Example total: $29,000.
- Deduction: $29,000
- Tax savings at 32%: $9,280
- Effective net cost: $19,720
Example
4. Multi-specialty clinic procedure suite (C corporation, 21% federal plus state)
Anesthesia machine ($25,000 example), two Omni III monitors ($12,000 example), S400 lights ($14,000 example), ST500 table ($20,000 example). Example total: $71,000.
- Deduction: $71,000
- Tax savings at 26%: $18,460
- Effective net cost: $52,540
Example
5. Mobile or office-based anesthesia provider (single-member LLC)
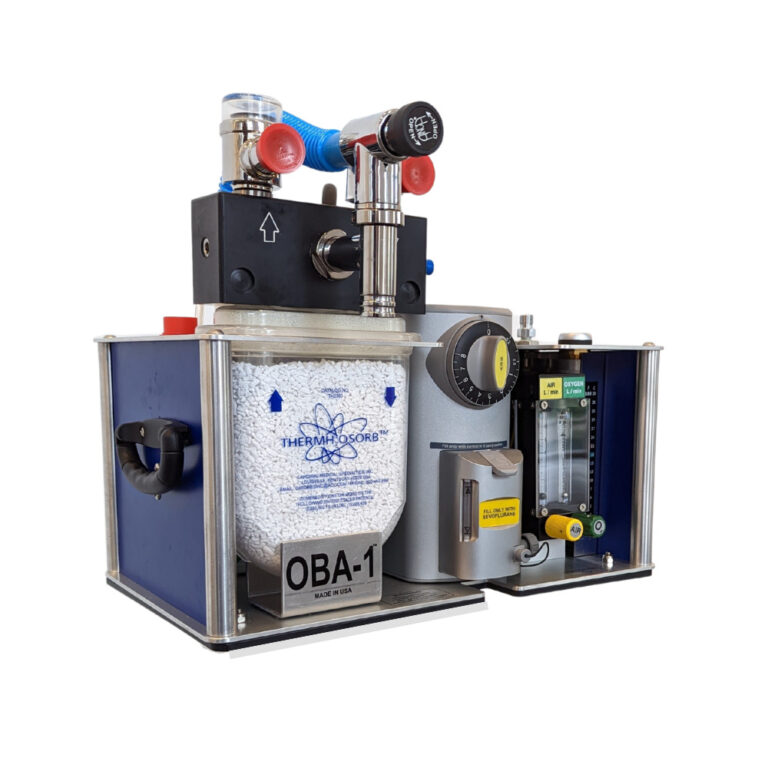
Two OBA-1 portable anesthesia machines ($36,000 example) and two Omni III monitors ($12,000 example), transported between client offices. Example total: $48,000.
- Deduction: $48,000
- Tax savings at 35%: $16,800
- Effective net cost: $31,200
Example
6. Large surgical group crossing the phase-out
A multi-site group places $4,400,000 of equipment in service in 2026 (example total, not an Infinium price). The limit drops by $310,000 (the amount over $4,090,000), to $2,250,000 (it would reach $0 at $6,650,000). The rest can be addressed with bonus depreciation; ask your tax advisor.
Calculator
Enter equipment cost, your combined tax rate, and business use percentage. The estimate applies the 2026 limit and phase-out. Results are estimates, not Infinium prices or tax advice.
Phase-out uses your total 2026 qualifying purchases.
Estimated tax savings
$22,750
- Section 179 deduction
- $65,000
- Effective net cost
- $42,250
Estimate only, using 2026 IRS limits. Assumes taxable business income covers the deduction. Not tax advice; consult your tax advisor.
FAQ
Is Section 179 a tax credit?
No. It is a deduction that reduces taxable income. Your savings equal the deduction multiplied by your tax rate.
What is the Section 179 limit for 2026?
$2,560,000, reduced dollar for dollar once qualifying equipment placed in service during the year exceeds $4,090,000. The limit reaches $0 at $6,650,000 (IRS Rev. Proc. 2025-32). Above the phase-out, the remaining cost can usually be deducted through 100% bonus depreciation instead.
Does the equipment have to be paid for by December 31?
It has to be placed in service, meaning installed and ready for use, by the end of your tax year. For calendar-year practices that is December 31, 2026. Financed equipment can qualify for its full cost.
Does used or refurbished equipment qualify?
Yes, if it is new to your practice and was not acquired from a related person or a member of the same controlled group (IRS Publication 946).
Do leased medical devices qualify?
A lease that works like a purchase, such as a $1 buyout lease, generally qualifies. A true operating lease does not.
Can a nonprofit hospital use Section 179?
Generally no. Tax-exempt organizations do not pay income tax on exempt activities, so the deduction provides no benefit.
What if my practice had a low-income year?
The deduction is limited to taxable business income. Any amount above that carries forward to future years. Bonus depreciation does not have this income limit; ask your advisor.
How do I claim it?
Your tax preparer elects Section 179 on IRS Form 4562 with your return.
Package Quote
Request a Package Quote
Tell us about your rooms and timeline. Mention Section 179 and the December 31 in-service date in your notes so we can plan delivery and installation.
Disclaimer: This page is for general information and is not tax, legal, or accounting advice. Section 179 eligibility and savings depend on your circumstances. Consult your tax advisor before making purchasing decisions. Figures reflect IRS guidance for tax years beginning in 2026 as of October 2026.